Top 5 Lenders for Motorcycle Loans for Bad Credit in 2026
Last updated: 2026-10-16
Trying to score a new bike when your credit score is in the gutter feels like hitting a brick wall. Many riders assume a bruised credit history means they are destined to ride a beat-up old machine forever. Perhaps you have a history of late payments or a high debt-to-income ratio. Maybe a recent bankruptcy is still haunting your reports. Regardless of the cause, being denied a loan when you have your heart set on a specific machine is incredibly discouraging.
The reality is that the lending world has shifted. The era of “one size fits all” banking is fading. It has been replaced by a fragmented market where specialized lenders find value in segments that traditional big-box banks often overlook. This list focuses on finding lenders who see the person behind the numbers. They offer pathways to ownership even when your financial past has been a bit bumpy or unpredictable. Whether you want a high-performance street bike or a reliable commuter, there is a financial lane carved out for you.
- Roadrunner Financial
- FastLendGo
- OneMain Financial
- SCU Credit Union
- Sound Credit Union
How We Evaluated These Lending Options
Evaluating lenders for bad credit requires a different lens than traditional prime lending. When you have a score above 740, lenders compete for your business with the lowest possible rates. When you are working with a score in the 500s or low 600s, the criteria shift. You stop asking “how much can they offer me?” and start asking “will they offer me anything at all?” We looked beyond just the lowest interest rates to see who actually provides accessibility for those with less-than-perfect scores.
It isn’t just about saying “yes.” We looked at how they say it, how they handle your data, and whether their terms are predatory or merely challenging. We prioritized speed and the ability to prequalify without hurting your score. We also looked at the breadth of vehicle types covered. A lender that only works with brand-new motorcycles isn’t helpful if you are hunting for a vintage cafe racer or a used dirt bike.
We also scrutinized the “hidden” costs. Items like origination fees or prepayment penalties can make a “cheap” monthly payment much more expensive in the long run. This is especially true if you plan to pay the loan off early once your credit improves. You don’t want to find out later that you’re locked into a high-cost contract just because the initial monthly payment looked low on the sticker.
| Lender Name | Loan Amounts | Terms | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| Roadrunner Financial | See site | See site | Quick Process | All credit welcome |
| FastLendGo | $500 – $5,000+ | See site | Quick access | Bad/Fair Credit |
| OneMain Financial | $1,500 – $30,000 | 24 – 60 months | As soon as 1 hour | See site |
| SCU Credit Union | See site | 60-month options | See site | New & Used vehicles |
| Sound Credit Union | See site | See site | See site | RV, Boat & Motorcycle |
1. Roadrunner Financial
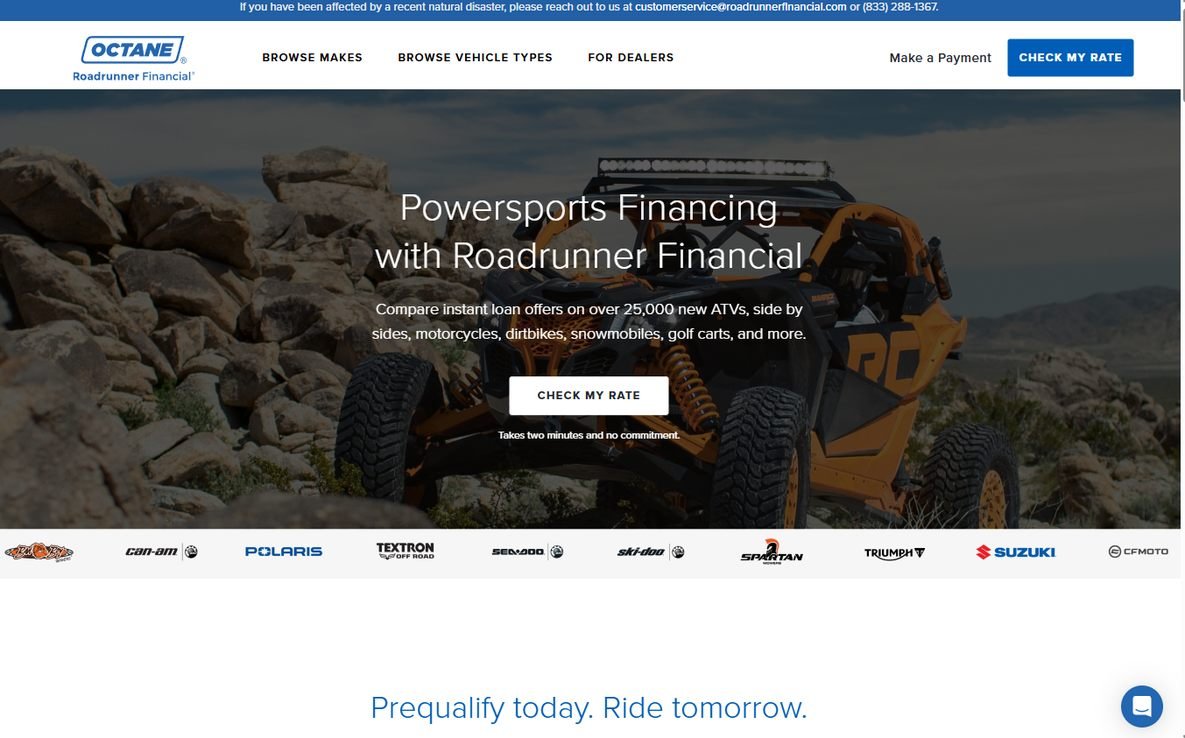
Roadrunner Financial acts as a bridge between riders and dealerships. They specialize in powersports financing, covering everything from ATVs and side-by-sides to dirtbikes and snowmobiles. It is a heavy hitter for anyone looking to secure a ride at a local dealership without the usual headache. Instead of you running from bank to bank, Roadrunner works with a network of dealers to streamline the approval process.
The standout feature here is the ability to check your rate in about two minutes. This process uses a “soft pull” mechanism. It doesn’t touch your credit score, so you can shop around without the fear of dropping your points further. This is a critical tool for anyone trying to gauge their purchasing power. For example, if you find a used Yamaha XT250 at a dealership, you can quickly see if Roadrunner can facilitate that specific purchase before you even drive to the lot.
Because they focus on the dealership model, they are highly integrated into the sales process. When you sit down with a salesperson, the financing is often already moving in the background. This makes the “buying experience” feel less like a negotiation and more like a transaction. This is especially helpful for those who find the high-pressure environment of a dealership intimidating.
Pros:
- Prequalify with no impact on credit score
- Covers a massive range of powersports including golf carts
- Real-time decisions to save time at the dealership
Cons:
- Primarily focuses on dealership-based financing rather than direct personal loans
2. FastLendGo
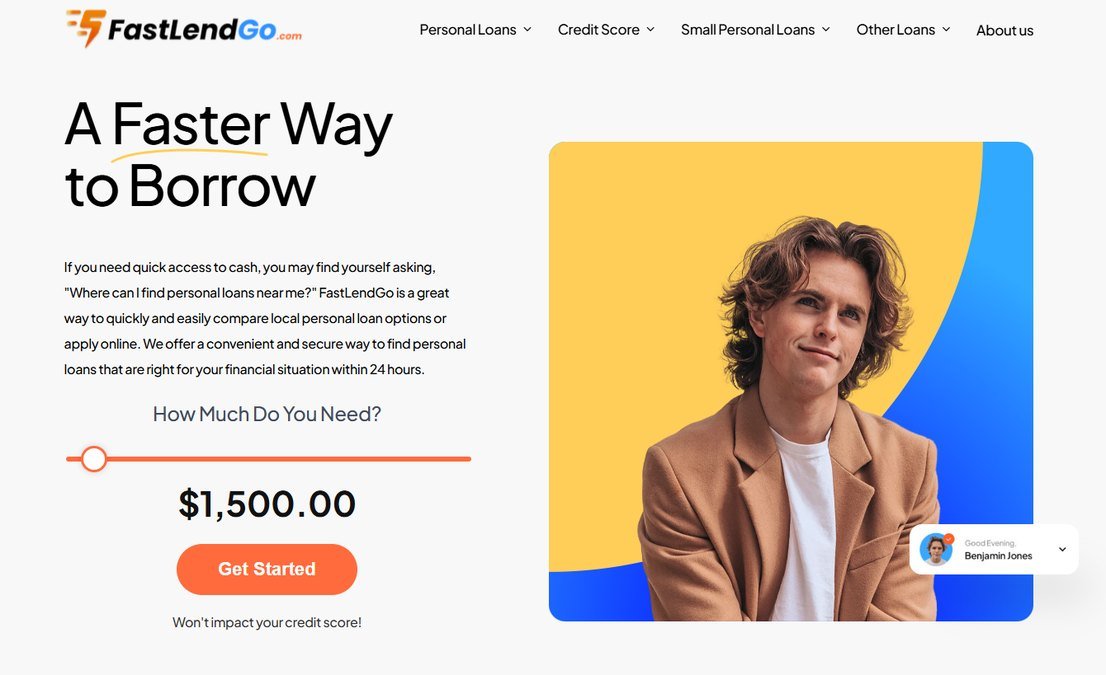
If you find yourself in a pinch and need cash to secure a deal, FastLendGo offers a direct path. They specialize in personal loans that cater specifically to those with bad or fair credit. Unlike traditional auto loans that are tied to a specific VIN, a personal loan from FastLendGo gives you the cash to buy a bike from a private seller on Craigslist or Facebook Marketplace. This is a common scenario for riders looking for deals on older, high-mileage bikes.
This lender is particularly useful for people who need quick access to cash for various needs, including motorcycle loans. They offer different tiers, from $500 up to $5,000 and beyond. This makes them a flexible partner for many different financial situations. For instance, if you need $2,000 to buy a used Honda Rebel from a private party, a traditional bank might refuse the loan because there is no collateral. FastLendGo’s unsecured personal loan model is designed for exactly this type of flexibility.
Pros:
- Specialized options for bad and fair credit
- Quickly compare local personal loan options
- Flexible loan amounts starting at $500
Cons:
- Interest rates for bad credit can be significantly higher than prime loans
3. OneMain Financial
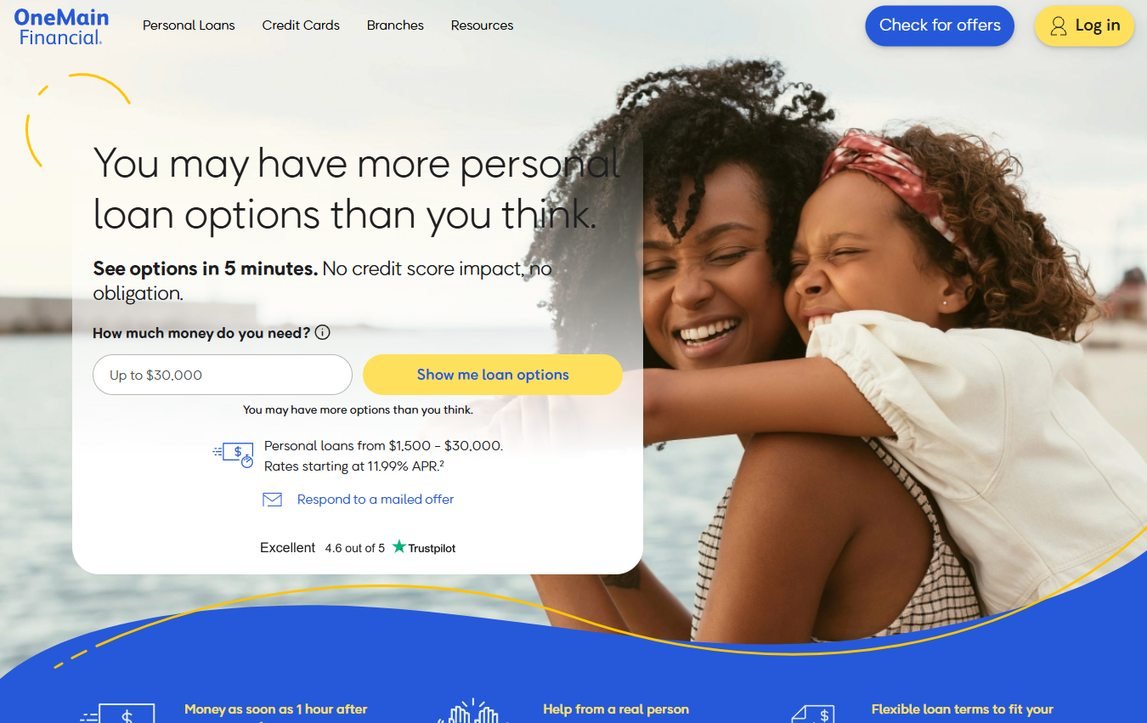
OneMain Financial is a massive player in the personal loan space, offering a structured approach to borrowing. They provide loans ranging from $1,500 up to $30,000, which covers the majority of used motorcycle price points. If you are looking to upgrade from a 250cc commuter to a mid-sized cruiser, OneMain’s loan ceiling is likely sufficient to cover the gap.
The speed of funding is impressive. You could have money available as soon as one hour after signing. This rapid turnaround is ideal for riders who have found a “unicorn” bike—a rare model that won’t be available by tomorrow. With fixed monthly payments and terms between 24 and 60 months, it provides a predictable way to manage your debt while you enjoy your new ride. You won’t have to worry about your payment amount changing halfway through the loan term.
Pros:
- Very fast funding, potentially within one hour
- Large loan amounts up to $30,000
- Fixed monthly payments for easier budgeting
Cons:
- Requires visiting a branch or interacting with their specific system
4. SCU Credit Union
Credit unions often hold the secret sauce for better rates. Unlike commercial banks that answer to shareholders, credit unions are member-owned non-profits. SCU Credit Union offers financing for both new and used motorcycles, including popular brands like Honda and Harley-Davidson. They are a great option for those looking to consolidate existing debt while getting a bike. If you have several high-interest credit card balances, using a SCU loan to roll those into one lower-interest payment can be a powerful way to clean up your balance sheet.
Because they are a credit union, the focus is often on the member’s long-term financial health. They tend to look at the “whole person.” They might consider your steady employment history or your community ties rather than just a single numerical score. Whether you are looking for a 60-month term or looking to build your savings simultaneously, they offer a suite of services that go beyond just the loan itself. They are an excellent choice for the rider who plans on staying with the same institution for years to come.
Pros:
- Financing available for new and used motorcycles
- Options to consolidate debt
- Expertise in various vehicle types
Cons:
- Membership requirements may apply to certain credit union benefits
5. Sound Credit Union
Sound Credit Union serves a wide variety of needs, including specialized loans for RVs, boats, and motorcycles. They are a comprehensive institution that looks at your total financial picture. This makes them a “lifestyle” lender for those who don’t just want a motorcycle, but perhaps a trailer to haul it or a boat for the weekend.
For the rider who wants a relationship with their bank, Sound is a strong contender. They offer specialized motorcycle loans that can help you get on the road while maintaining a banking relationship for your future financial needs. This relationship can be invaluable. Once you have established a history of on-time payments with Sound, your next loan—perhaps for a car or a home down payment—may be much easier to secure.
Pros:
- Specialized motorcycle and powersports loan focus
- Full suite of banking services available
- Comprehensive financial support
Cons:
- Might require more paperwork compared to instant-decision online lenders
Preparation: Improving Your Chances Before You Apply
While the lenders listed above are willing to work with less-than-perfect credit, your chances of securing a lower interest rate increase significantly if you take proactive steps before hitting the “apply” button. Think of this as “pre-flighting” your financial situation.
First, pull your credit report from all three major bureaus (Equifax, Experian, and TransUnion) to ensure there are no errors. A single incorrect late payment reported by a previous landlord or a utility company can tank your score by 50 points. If you find errors, dispute them immediately. A “pending dispute” status can sometimes be taken into account by manual underwriters.
Second, prepare a “financial dossier.” When dealing with lenders like Sound or SCU Credit Union, being able to immediately provide two months of pay stubs, proof of residence, and a clear summary of your monthly expenses can set you apart. It demonstrates that you are a responsible, organized individual. This builds trust, which is the most important currency in the world of subprime lending.
Third, consider a co-signer. If you have a family member with strong credit who is willing to back you, this can be a game-changer. A co-signer essentially tells the lender, “If this rider fails to pay, I will.” This significantly lowers the lender’s risk. It can often move you from a “denied” status to an “approved” status with a much more manageable interest rate.
Navigating the Road Ahead
Before you sign on the dotted line, remember that a loan is a commitment. When dealing with bad credit, the interest rate is often the price you pay for the privilege of immediate ownership. It is vital to look at the total cost of the loan, not just the monthly payment. A $200 monthly payment might seem manageable, but if that payment is spread over 72 months at 18% interest, you will end up paying nearly double the actual value of the motorcycle.
Always ask for the “Truth in Lending” disclosure. This is a standardized document that lenders are legally required to provide. It breaks down the total amount you will pay over the life of the loan, including all interest and fees. If a lender is hesitant to provide this or tries to hide the total cost in fine print, walk away immediately.
Avoid the mistake of rushing into a deal just because a dealer is pushing you to sign. High-pressure sales tactics are common in powersports, especially when they know your credit is a weak point. They may try to offer you a “no money down” deal that looks attractive, but it carries an astronomical interest rate that keeps you in debt for years. Take a moment to compare the offers you received during the prequalification stage. A little bit of patience now can save you thousands of dollars in interest. Your goal shouldn’t just be to get a bike; it should be to get a bike and remain financially free while riding it.