Top 4 Dental Financing Options Ranked for 2026
Last updated: 2026-10-16
Walking into a dentist’s office only to receive a price tag that feels like a punch to the gut is a common nightmare. Most people find themselves staring at a bill for implants or crowns, wondering if they will ever see their bank account balance rise again. Whether it is an emergency root canal necessitated by a sudden infection or a planned cosmetic procedure like veneers that promises a total transformation, the upfront cost can be staggering. Finding a way to bridge that gap without breaking the bank is essential for maintaining both your physical health and your financial stability.
Choosing the right way to pay for your smile isn’t just about the monthly payment. It involves looking at interest rates, how a lender treats your credit score, and how quickly you can get the green light. A high interest rate might make the monthly installment seem manageable, but over a 24-month period, you could end up paying thousands more than the actual cost of the dental work. Conversely, a lender that requires an impeccable credit score might leave you in pain while you wait weeks for an approval. This ranking looks at the most prominent players in the market to help you decide which path leads to a healthy smile.
- CareCredit
- Cherry
- FastLendGo
- iCare
How These Dental Payment Solutions Were Evaluated
The selection process focused on the specific needs of patients facing unexpected oral health costs. We looked at whether a lender provides quick decisions, which is vital when a toothache won’t quit. Speed often matters just as much as the actual cost of the loan when you are in pain. If you are sitting in a waiting room with a throbbing molar, you don’t want to be told you have to wait three business days for a manual underwriting process to finish. You need a solution that works in real-time.
We also weighed the accessibility of these options for individuals with varying credit profiles. Some patients have pristine scores and can qualify for the lowest possible APRs, while others are just trying to keep their heads above water and may have a history of late payments or high credit utilization. A good financing partner should offer a way forward, regardless of whether your credit history is a polished gem or a bit of a mess. We evaluated lenders based on three primary pillars: speed of approval, ease of application, and the breadth of credit eligibility. We also considered the “hidden” costs, such as origination fees or penalties for early repayment, which can turn a simple payment plan into a long-term debt trap.
| Lender Name | Primary Use Case | Speed of Decision | Credit Requirement | Loan Amounts |
|---|---|---|---|---|
| CareCredit | Health & Wellness | Instant | Subject to Approval | See site |
| Cherry | Flexible Payment Plans | Fast | Broad Eligibility | See site |
| FastLendGo | Personal Loans | Quick | All Credit Tiers | $500 – $5,000+ |
| iCare | No-Nonsense Financing | Instant | No Credit Check | See site |
Understanding the Cost of Delaying Care
It is tempting to push a dental bill to the “next month” pile, but in dentistry, procrastination is often the most expensive financial decision you can make. Oral health issues are rarely static; they are progressive. A small cavity that costs $200 to fix today can evolve into a cracked tooth requiring a $1,500 crown in six months, or an even more expensive $2,500 root canal and buildup if the infection reaches the nerve.
When comparing financing options, it is helpful to view the cost of the loan against the cost of the untreated condition. If a lender offers a 0% interest plan for six months, the “cost” of the money is effectively zero, making it a highly efficient way to manage cash flow. However, if you choose a high-interest personal loan to avoid a waiting period, you must calculate if the interest paid is less than the projected increase in the cost of the dental procedure if it worsens. In many cases, the interest on a loan is a small price to pay to prevent a surgical emergency later.
Ranking the Best Lenders for Your Dental Care
1. CareCredit
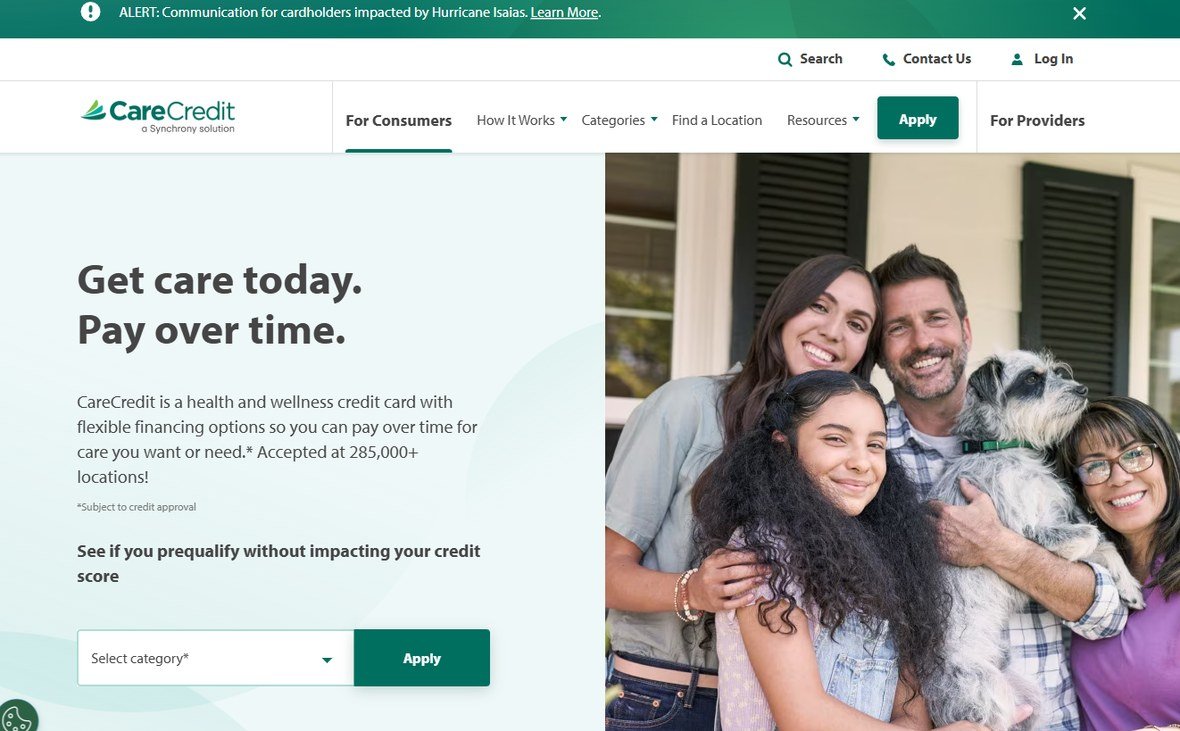
CareCredit operates as a specialized health and wellness credit card designed for medical and dental needs. It is a heavy hitter in the industry, accepted at over 285,000 locations. This makes it a very convenient choice if your dentist is already part of their vast network of providers. Because it is a dedicated credit line, it doesn’t clutter your primary personal credit card utilization, which can help keep your credit score stable if managed correctly.
The application process is designed to be painless, offering instant credit decisions so you aren’t left waiting. It is an ideal solution for those who want a dedicated line of credit specifically for health-related expenses and want to pay over time. Many providers offer “deferred interest” promotions—for example, 6, 12, or 24 months of 0% interest. This is a powerful tool, but it comes with a significant caveat: if you fail to pay the full balance by the end of the promotional period, you are often backdated and charged all the interest that would have accrued from day one. You must be disciplined to make this work.
Pros:
- Extremely wide acceptance at dental offices nationwide.
- Instant decisions mean you can start treatment quickly.
- Prequalification does not impact your credit score.
Cons:
- Subject to credit approval and standard card terms.
2. Cherry
Cherry has carved out a niche by offering more modern, patient-friendly payment plans. They are known for having broader eligibility criteria, which is a breath of fresh air for those who might be nervous about traditional bank loans. It feels less like a rigid contract and more like a helpful tool. Instead of a revolving credit card, Cherry often functions more like a structured installment loan, where you know exactly how much you owe and when each payment is due.
This option is perfect for patients who want a straightforward payment structure without the heavy lifting of traditional credit cards. It aims to make ownership of your dental care feel immediate and much less intimidating for the average person. Because Cherry integrates directly with many dental practice management softwares, the checkout process at the dentist’s office is often as simple as a few clicks on a tablet, allowing you to walk out with your treatment scheduled and your financing settled in minutes.
Pros:
- Broad eligibility criteria for a wider range of people.
- Provides a flexible alternative to standard credit cards.
- Streamlined process for quick payment plan setups.
Cons:
- May not offer the same high limits as traditional credit lines.
3. FastLendGo
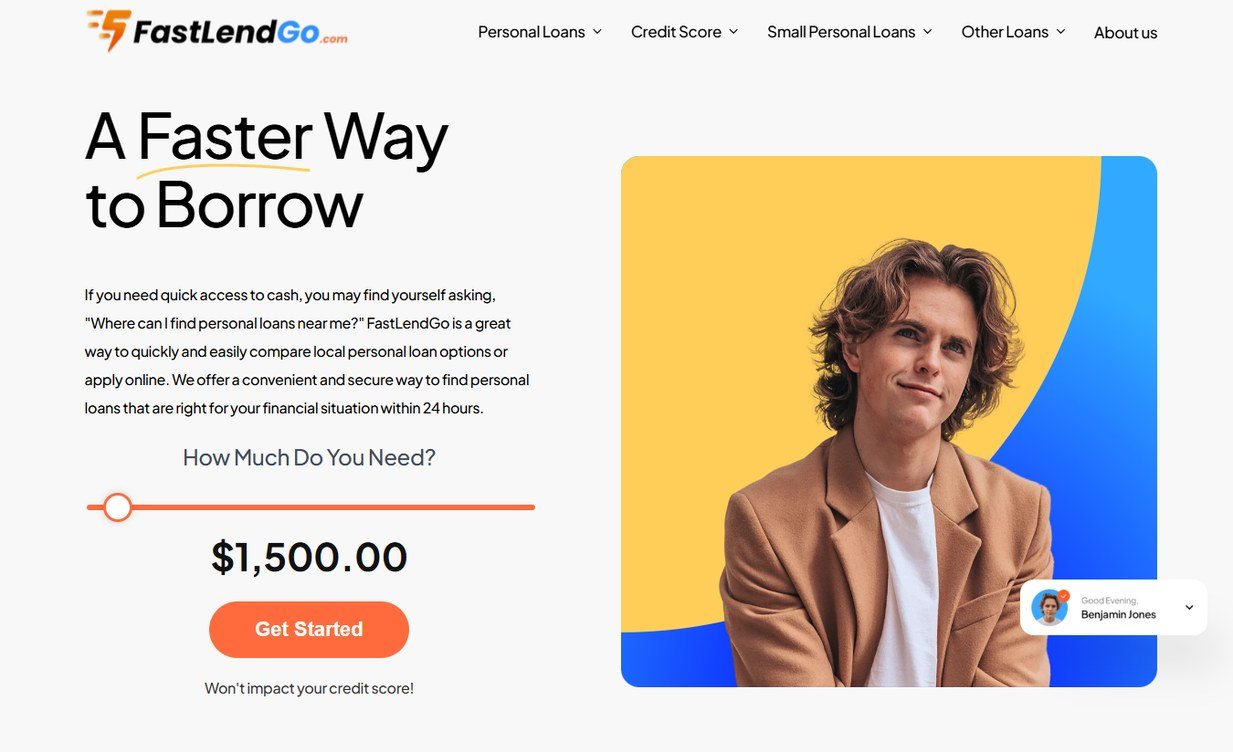
FastLendGo acts as a versatile partner for various personal financing needs, including dental work. They cater to a wide spectrum of borrowers, from those with great credit to those struggling with bad credit. This makes them a go-to for people who need a personal loan specifically for dental care where the dentist’s in-house financing might be too restrictive or unavailable. Unlike a credit card, which you use at the point of sale, a personal loan from FastLendGo is often deposited directly into your bank account.
If you need a lump sum of cash to cover a large procedure, this is a strong contender. They offer various loan sizes, starting from small amounts like $500 up to $5,000 or more, making them quite flexible for different treatment scales. This is particularly useful if you are paying a dentist who does not participate in any third-party financing programs. Having the cash in hand allows you to negotiate a “cash discount” with some providers, which can sometimes offset the interest cost of the loan itself.
Pros:
- Accepts various credit levels, including bad credit.
- Offers specific loan amounts for different needs.
- Quick access to cash for immediate dental repairs.
Cons:
- The interest rates can vary significantly based on credit.
4. iCare
iCare takes a very different approach with its patented, no-nonsense program. The standout feature here is the ability to offer 0% interest financing with no credit check and instant approval. This is a game-changer for patients who cannot afford to wait or undergo a rigorous credit investigation. For many, the idea of a “credit check” is a source of immense anxiety, fearing that a rejection will further damage their score or that a high-interest rate will follow them for years.
This option is tailor-made for the patient who needs a customized, hassle-free way to pay for care. It removes the “fear factor” often associated with financing, allowing the focus to remain on oral health rather than financial anxiety. It is an ideal bridge for those who might be in a temporary cash crunch but have a steady income that supports monthly installments. By decoupling the financing from traditional credit scoring, iCare opens doors for many who would otherwise be forced to delay essential care.
Pros:
- Offers 0% interest options.
- No credit check required for instant approval.
- Highly customizable financing structures.
Cons:
- Availability may depend on the specific provider’s setup.
Comparing Financing Types: Credit Cards vs. Personal Loans vs. Installment Plans
To choose the best path, you must understand the structural differences between these financial tools. Not all “debt” is created equal, and the way you repay it determines your long-term financial health.
| Feature | Credit Card (e.g., CareCredit) | Personal Loan (e.g., FastLendGo) | Installment Plan (e.g., Cherry) |
|---|---|---|---|
| Structure | Revolving (can be used repeatedly) | Lump Sum (one-time use) | Fixed Term (fixed monthly payments) |
| Interest Type | Often promotional 0% (then high APR) | Fixed APR throughout term | Typically fixed or low-cost |
| Impact on Credit | Affects utilization and payment history | Affects debt-to-income ratio | Minimal impact if structured as a service |
| Best For | Long-term, high-value procedures | When you need cash in your own bank account | Predictable, monthly budgeting |
Avoiding Common Financial Pitfalls
Before you sign on the dotted line, always look at the fine print regarding interest. It is easy to get caught up in the excitement of a “no credit check” offer, but you must understand if the total cost of the procedure increases significantly due to fees or deferred interest. For instance, if a plan offers 0% interest for 12 months but charges a 5% “origination fee” upfront, your actual cost of borrowing is higher than it appears. Always ask your dentist how they handle these specific providers and if there are any administrative fees associated with setting up the plan.
Another mistake is ignoring the impact on your budget. A monthly payment might look small on paper—say, $75 a month—but when stacked with a car payment, a phone bill, and rising grocery costs, it can become a mountain that is difficult to climb. A “payment shock” occurs when a patient realizes they have committed to several different financing plans at once. Make sure the payment schedule fits your lifestyle, not just your immediate need for a new tooth. Always aim to pay off your dental financing as quickly as possible; even if you have a 0% interest plan, paying it off early provides peace of mind and frees up your monthly cash flow for other life necessities.