Top 6 Lenders for a Personal Loan with a Co-Signer in 2026
Last updated: 2026-10-16
Trying to find a lender when your credit score is lagging can feel like walking through a thick fog without a map. Bringing in a co-signer often acts as a lighthouse, helping you find better rates and a higher chance of approval. Just remember, this is a massive commitment for everyone signing the paperwork.
This list highlights lenders that offer flexibility for anyone needing a second pair of hands to back their debt. You might be looking to roll several bills into one or fix a leaky roof. Knowing which lenders are willing to play ball is a big part of staying financially healthy.
- OneMain Financial
- JetzLoan
- Reprise
- Prosper
- LendingPoint
- Acorn Finance
How These Lending Options Were Evaluated
We picked lenders that show a willingness to work with various credit profiles. A co-signer with a FICO score around 670 or higher can often unlock much better terms than a borrower could find on their own. We looked for companies that keep their processes transparent and get funds out quickly.
Speed and ease of use were major factors in our scoring. We prioritized companies that let you check rates without a hard credit pull, since you don’t want to tank your score just to see your options. This list reflects a mix of old-school stability and fast, digital-first speed for the 2026 market.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact for Check | Terms/Details |
|---|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | As soon as 1 hour | No impact | 24-60 months |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No impact | Up to $50k max |
| Reprise | see site | see site | see site | AI Demo Platform |
| Prosper | $2,000 – $50,000 | Fast | No impact | Up to 6-year terms |
| LendingPoint | $1,000 – $36,500 | see site | No impact | see site |
| Acorn Finance | see site | Just now | No impact | Home Improvement Focus |
Top Ranked Lenders for Co-Signed Borrowing
1. OneMain Financial
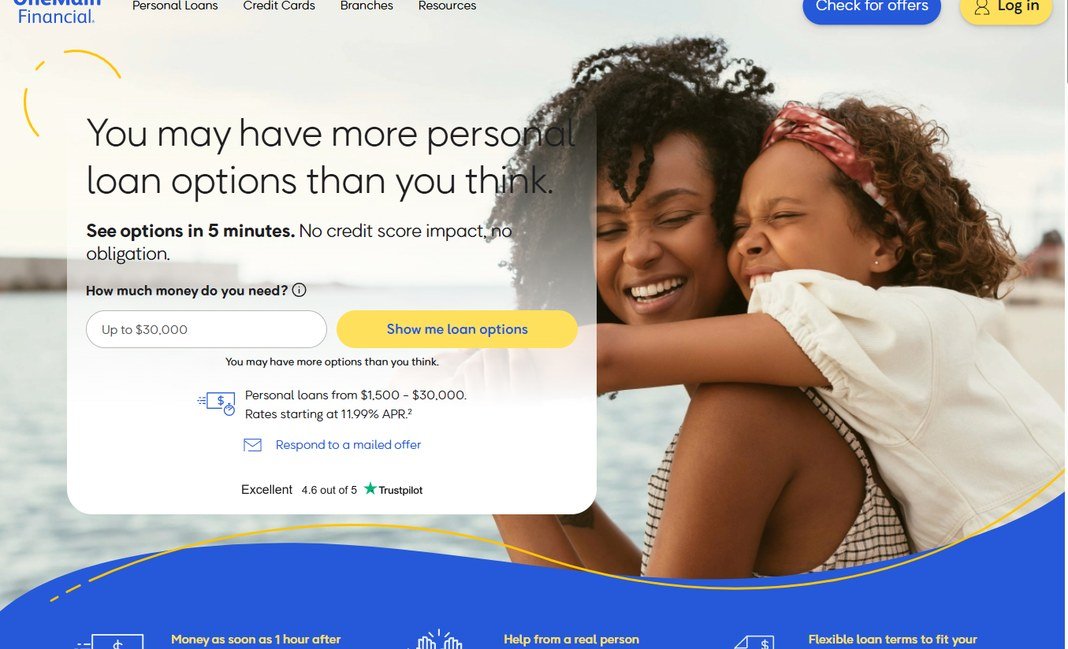
OneMain Financial is a heavy hitter in the personal lending world. They are a great fit for people who might need a little extra help because of less-than-perfect credit. By letting you add a co-signer, they help turn a potential “no” into a “yes” for many applicants.
The speed they offer is impressive for a traditional lender. You can see your options in five minutes and potentially see funds hit your account just an hour after signing. That is a total lifesaver when you are facing an urgent situation and time is running out.
With fixed monthly payments and terms from 24 to 60 months, you know exactly what to expect. Having a real person you can call or visit at one of their 1,300 branches provides a safety net that purely digital apps often miss.
Pros:
- Very fast funding, potentially within an hour.
- Large branch network for in-person support.
- No credit score impact when checking offers.
Cons:
- Interest rates can be high for those with poor credit.
2. JetzLoan
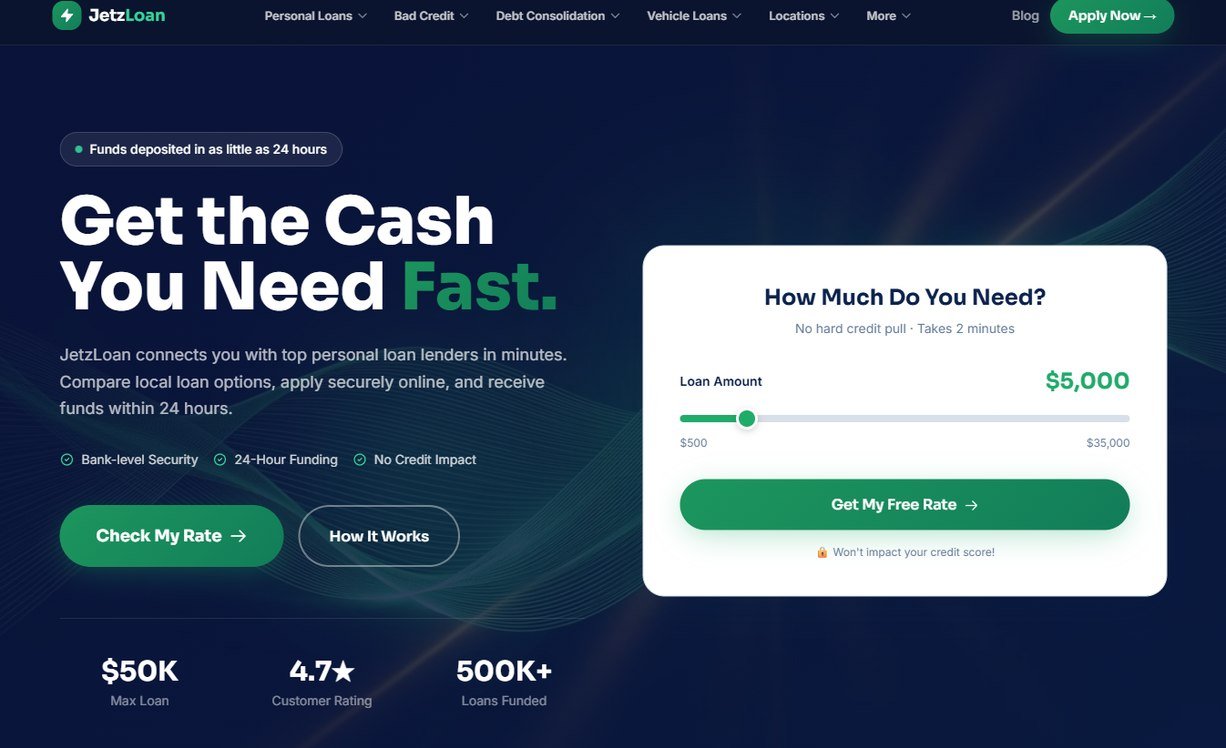
JetzLoan works like a high-speed connector in our digital age. They don’t make you jump through endless hoops. Instead, they try to connect you with top lenders in just a few minutes. It is a streamlined experience built for a busy life. (jetzloan.com)
The whole platform is built for speed. They claim funds can land in your account in as little as 24 hours, which makes them a top choice if you are dealing with a sudden financial hurdle. The interface is simple, so the application feels like a quick task rather than a chore.
Since they focus on bad credit and debt consolidation, they serve a crowd that big banks often ignore. They promise a process that is relatively stress-free, focusing on getting you cash without the usual headache.
Pros:
- Extremely quick 2-minute application process.
- No hard credit pull to check rates.
- High customer satisfaction rating.
Cons:
- The platform is a connector, not the direct lender.
3. Reprise
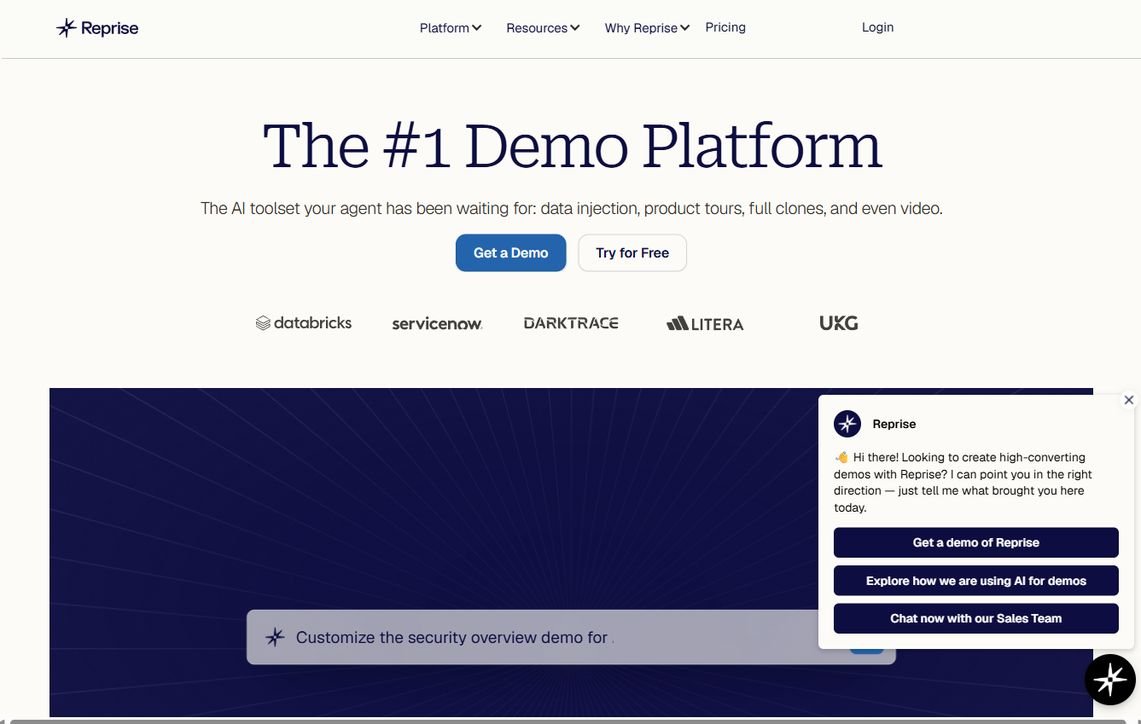
Reprise is a bit of an outlier on this list because they occupy a different niche entirely. They are an AI toolset for creating enterprise demos. While they don’t give out personal consumer loans, they are a big deal for professionals working in tech.
Their platform lets agents build high-quality, data-driven demos using AI. It helps sales teams show off their products using realistic data and smooth transitions. It is a tool meant for boosting productivity, not for paying off personal debt.
If you want to boost your company’s sales capabilities, this is a powerhouse. However, if you are looking for a co-signed loan to cover your bills, you will find their services totally irrelevant to your needs.
Pros:
- Powerful AI-driven demo creation tools.
- Seamless data injection for product tours.
- Helps sales agents become much more capable.
Cons:
- Not a personal loan provider for consumers.
4. Prosper
Prosper is a well-known name in the peer-to-peer lending world. They offer a flexible approach, with loan amounts from $2,000 up to $50,000. Their whole setup is based on connecting individual lenders with borrowers who need a helping hand.
They recently added 6-year terms to their lineup, which gives you more breathing room for monthly payments. This kind of flexibility is a godsend if you are trying to manage your cash flow while chipping away at significant debt.
Prosper gets high marks for ease of use. You can see your rates in about a minute. They also offer a variety of other products like credit cards and investing options, making them a one-stop shop for many users.
Pros:
- Longer 6-year terms available for more flexibility.
- Quick rate checks with no impact on credit.
- Strong reputation in the peer-to-peer space.
Cons:
- Peer-to-peer models can sometimes have variable availability.
5. LendingPoint
LendingPoint handles a variety of life events, from unexpected medical bills to home improvements. They offer a wide range of amounts, starting at $1,000 and going up to $36,500. This versatility makes them a good fit for many different situations.
The platform is designed to make money simple. You can check your rate without it touching your credit score, which is vital when you are shopping around for the best deal. You want to compare options without the penalty of a hard pull.
They cover everything from debt consolidation to wedding financing. This range, combined with how they handle different credit profiles, makes them a reliable option for many households.
Pros:
- Wide range of loan amounts to suit different needs.
- No credit score impact when checking rates.
- Covers many different personal loan purposes.
Cons:
- Terms and rates are not always explicitly listed upfront.
6. Acorn Finance
Acorn Finance takes a specialized path by focusing heavily on home improvement. They act as a marketplace that links borrowers with contractors and financing options specifically for projects like kitchen remodels or pool installs.
They are particularly useful if you need a large sum for a major renovation. Their system is fast; some people get offers minutes after applying via email or SMS. It is a very modern way to handle contractor financing.
Whether your credit is good or bad, Acorn Finance tries to find personalized rates. They use a “zero dealer fee” model, which can save you a lot of money when you are dealing with expensive home projects.
Pros:
- Specialized in home improvement and contractor financing.
- Extremely fast response times for offers.
- No dealer fees for the borrower.
Cons:
- Highly specialized, which might not suit non-home projects.
Navigating the Co-Signer Process
Picking a lender is only half the battle; you also have to pick the right co-signer. This person should have a strong FICO score and a steady income. They are essentially telling the lender, “If this person fails, I will pay the debt.” That is a massive weight to carry, and it can hurt their own credit if things go sideways.
Don’t make the mistake of rushing into a loan just because a lender accepts a co-signer. You must sit down with that person and talk through a real repayment plan. You don’t want a financial emergency to turn into a massive fight with a family member. Open communication is your most important tool here.
Finally, keep a close eye on the total cost of the loan. A lower interest rate sounds great, but if the term is too long, you might end up paying much more in total interest over time. Do the math before you sign anything to ensure the loan stays a help rather than a burden.